
Trends in the Dominance of Korea’s Memory Duo (Samsung/SK Hynix) in the MSCI Korea Index
AI storage and computing power are not abstract concepts in Korea. They are embodied in two names: Samsung Electronics and SK Hynix. Together, this memory duo has become so dominant that the MSCI Korea Index—and any ETF or index derivative tied to it—is increasingly a leveraged bet on AI memory cycles. Understanding how their dominance has evolved, and what it implies for AI storage and compute exposure, is essential for anyone trading Korea-focused ETFs or using index derivatives as hardware proxies.
Over the last two decades, these two companies have moved from important components of Korea’s market to its structural anchors. Today, they account for a very large share of MSCI Korea’s weight, meaning their price movements effectively drive index returns. That concentration is both a strength and a vulnerability. It gives Korea ETFs significant exposure to AI storage and computing power, but it also ties their fate closely to memory cycles and capital flows into just two stocks.
How Dominance Emerged: From Leaders to Pillars
Samsung and SK Hynix have long been key players in memory—DRAM, NAND, and now HBM. As global demand for digital devices grew, their importance increased. But it is the AI wave, and the resulting memory supercycle, that pushed their dominance into a new phase. Memory chips became central to AI training and inference, and the companies supplying them became central to Korea’s market narrative.
As their market caps surged, so did their index weights. In MSCI Korea, Samsung and SK Hynix now represent a very substantial share of total index weight—often more than half, and at times approaching levels where they effectively dominate index behavior. This is not just a result of index design. It reflects the reality that Korea’s most globally relevant companies are its AI memory champions.
That trend has been reinforced by foreign capital. As global investors sought AI hardware exposure, they poured money into Samsung and SK Hynix. The MSCI Korea index, built around market capitalization, magnified that effect.
What Dominance Looks Like in MSCI Korea
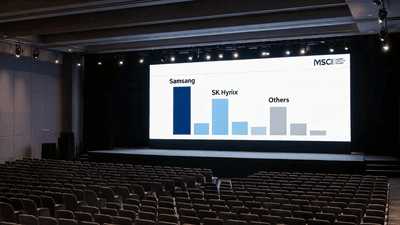
In practical terms, the dominance of Samsung and SK Hynix in MSCI Korea means:
- They are the largest constituents by far, and their combined weight can exceed half of the index.
- Index performance is highly sensitive to their price moves; large gains or losses in these two names can overshadow the contribution of dozens of smaller companies.
- Any MSCI Korea ETF or index derivative is implicitly a memory-heavy AI infrastructure product, even if marketed as a broad Korea equity tool.
For ETF and index derivative users, Korea-focused products now behave less like country diversification tools and more like theme vehicles. The theme is AI memory and advanced semiconductors, with other sectors in supporting roles.
AI Storage and Computing Power: Korea as a Memory Proxy
From an AI storage and computing power perspective, Korea’s memory duo turns MSCI Korea into a proxy for AI hardware. Samsung and SK Hynix produce DRAM and HBM chips that feed GPUs and accelerators in AI data centers around the world. Their capex plans, pricing decisions, and technology roadmaps are directly linked to AI storage capacity and performance.
When AI memory demand surges—due to larger models, more inference traffic, or new AI services—Samsung and SK Hynix benefit. Their index weights ensure that MSCI Korea reflects that benefit. In this sense, the dominance trend has made Korea a strategic AI storage and compute exposure, not just an emerging market allocation.
The flip side is that any slowdown in AI memory demand or normalization in pricing will affect MSCI Korea disproportionately. The index is tied to the memory cycle more tightly than ever.
Implications for Korea ETFs and Index Derivatives
For Korea ETFs and index derivatives, Samsung and SK Hynix’s dominance has several implications:
- Theme drift: Products marketed as “Korea equity” are heavily influenced by AI memory and hardware cycles.
- Sector bias: Memory and AI hardware now play a larger role in index behavior than many other sectors combined.
- Risk concentration: Country risk is tied closely to two names, reducing diversification and increasing idiosyncratic exposure.
Investors using MSCI Korea ETFs or futures need to understand that they are not just holding broad Korean equity. They are holding significant exposure to AI storage and computing power via Samsung and SK Hynix. That may be desirable for AI-themed portfolios, but it should be explicit in risk analysis and allocation decisions.
Index derivative users can also exploit this link. MSCI Korea future or option positions can act as AI memory expressions, with the caveat that they also carry non‑hardware Korean exposures.
Trend Drivers: AI CapEx, Policy, and Global Flows
The dominance trend is driven by three main forces:
- AI capex: Hyperscaler and cloud capex for AI infrastructure has turned memory into a strategic resource. Samsung and SK Hynix are central suppliers, pushing their valuations and index weights higher.
- Policy and industrial strategy: Korea’s policy environment supports semiconductor investment and global leadership. That reinforces corporate growth and investor confidence in the memory duo.
- Global capital flows: Foreign investors seeking AI hardware exposure have funneled capital into Samsung and SK Hynix, often via MSCI Korea and related ETFs.
These forces are not static. AI capex could moderate; policies could shift; foreign flows could rotate. But as long as the AI memory story remains strong, the dominance of the memory duo in MSCI Korea is likely to persist, even if weights fluctuate.
Risk: When Dominance Becomes Overreliance
Dominance can be a strength, but it can also become overreliance. For MSCI Korea, heavy dependence on two companies introduces risks:
- Cycle risk: The memory cycle’s ups and downs directly impact the index. A downturn in DRAM/HBM pricing can weigh heavily on index returns.
- Company-specific risk: Regulatory issues, operational setbacks, or strategic missteps at Samsung or SK Hynix can affect the entire Korea ETF.
- Valuation risk: If the market prices AI memory too optimistically, a correction in one or both companies can have outsized index impact.
For investors, the trend in dominance requires careful position sizing and awareness. Treating MSCI Korea ETFs as simple diversifiers without recognizing this concentration is a mistake. Allocation to Korea should be evaluated partly as allocation to AI memory and advanced semis.
Active Strategies: Using Dominance for AI Hardware Exposure
On the positive side, the dominance of Samsung and SK Hynix can be used actively in AI storage and computing power strategies:
- AI memory sleeve: MSCI Korea ETFs can serve as an AI memory sleeve in multi-region AI hardware portfolios, complementing U.S. compute and global equipment exposure.
- Relative value trades: Investors can trade MSCI Korea versus other AI hardware indices to express views on memory vs compute or Korea vs other hubs.
- Hedging: MSCI Korea derivatives can be used to hedge AI memory risk in portfolios heavily exposed to direct memory stock positions.
This active use turns the concentration trend into a feature rather than a bug. It recognizes that Korea’s equity benchmark has become an AI infrastructure tool and leverages that fact in portfolio construction.
Investor Behavior Evolution
Investors are already adapting to the new reality. Behavior trends include:
- Theme-first allocation: Some allocators now treat Korea ETFs as part of AI hardware sleeves rather than purely geography-based exposures.
- Single-stock substitutes: Others use MSCI Korea ETFs as substitutes for direct Samsung/SK Hynix exposure, preferring the flexibility of the ETF wrapper.
- Risk-aware marginal allocations: More sophisticated investors limit Korea exposure based on their overall memory and AI hardware risk budget, not just emerging market weight.
As dominance trends solidify, behavior will likely continue to shift from country framing to thematic framing. Korea becomes “memory + emerging market overlay” rather than “emerging market with some memory.”
What This Means for AI Storage and Compute Index Design
For designers of AI storage and computing power indices, the Korea memory duo’s dominance raises design questions:
- Should AI hardware indices cap the weight of Samsung and SK Hynix to manage concentration risk?
- Should separate AI memory indices exist that blend Korea with other suppliers to reduce single-country exposure?
- How should index methodologies treat cross‑listed or multi‑segment firms like Samsung that span memory, logic, and devices?
By 2027 and beyond, we can expect more nuanced AI hardware index structures that reflect these questions—blending Korea’s memory heavyweights with broader global memory and compute exposure while still recognizing their central role.
Index derivative users will then have more refined tools to express AI storage and compute views without relying solely on MSCI Korea as a proxy.
Conclusion
The trend in the dominance of Korea’s memory duo—Samsung Electronics and SK Hynix—in the MSCI Korea Index tells a clear story: AI memory and advanced semiconductors have become the gravitational center of Korea’s market. MSCI Korea and related ETFs are no longer just country exposures; they are heavily tilted AI hardware instruments, with memory at the core.
For ETF and index derivative users focusing on AI storage and computing power, this dominance is both an opportunity and a risk. It offers a powerful way to access AI memory cycles through Korea-focused products, but it also requires careful recognition of concentration, cyclicality, and company-specific exposures. As investor behavior evolves and product design matures, the role of Korea’s memory champions in AI hardware portfolios will remain central—and understanding that role will be essential to intelligent allocation in the AI era.
You May Like

Narrowing Spread Between NAND Spot and Contract Prices in 2026 – A Signal
By 2026, one of the most watched metrics in the NAND flash market has started to shift in a subtle but meaningful way: the spread between spot prices and long‑term contract prices is narrowing. For casual observers, this may look like just another incremental change in a notoriously volatile industry. For memory makers, module houses, device OEMs, and data center buyers, however, a tightening gap between spot and contract prices is a signal—a reflection of evolving supply–demand balance, risk perceptions, and strategic behavior on both sides of the market.

Price Divergence Trading Strategies Between NAND Flash and DRAM ETFs
NAND flash and DRAM sit at the core of AI storage and computing power. Both are memory, but they are not the same business. DRAM is main memory—fast, volatile, and central to high‑bandwidth workloads like AI training and inference. NAND is non‑volatile storage—slower than DRAM, but crucial to persistent data and large‑scale object storage. The cycles that drive their pricing and margins overlap, yet they often diverge. That divergence is where trading strategies between NAND and DRAM ETFs become interesting.

China’s HBM Localization Progress: The Catch-Up Pace of CXMT and XMC
China’s drive to localize advanced memory technologies has accelerated over the past several years. High-Bandwidth Memory (HBM) sits near the center of that strategy because it is integral to AI accelerators, high-performance computing (HPC) and other strategic compute platforms. Two domestic players—ChangXin Memory Technologies (CXMT) and XMC (Xianghui Memory, commonly referred to as XMC)—have become focal points in assessing how quickly China can close the gap with international incumbents on HBM die, stacking, and packaging.

Thermal Simulation Challenges and Solutions in 3DIC AI Chip Design
As AI workloads push chips to deliver ever higher compute density, designers are increasingly turning to three‑dimensional integration (3DIC) to stack dies vertically and pack more functionality into limited footprints. While 3DIC architectures unlock significant performance and bandwidth advantages, they also introduce complex thermal behaviors that are far harder to predict and manage than in traditional 2D layouts.

An Attempt at Compiling a Memory+Compute Fusion Thematic Index – A Dual-Track Framework
Most AI investors talk about “compute” as if it were the whole story: GPUs, accelerators, chips, cores. But every one of those cores needs somewhere to read from and write to. Memory and storage define how wide the data highway really is. In practice, AI performance is a fusion of compute and memory, not a solo act. So why do so many indices and ETFs separate them into different silos—one for semiconductors, one for memory, one for data centers—when the actual workloads keep blending them?

Surging Demand for Laser Drilling and Plasma Dicing Equipment in Advanced Packaging
Advanced packaging has become one of the semiconductor industry’s most important growth engines, and it is now pulling a surprising set of process tools into the spotlight. Among the most in-demand are laser drilling and plasma dicing equipment. These machines sit close to the heart of heterogeneous integration, fan-out packaging, wafer thinning, TSV formation, glass substrate processing, and other advanced flows where precision, yield, and throughput matter enormously. As packaging moves from a back-end afterthought to a strategic platform, the equipment used to shape, open, and separate materials has become just as important as the dies themselves.

D2D Interface Bandwidth and Latency Comparison in Chiplet Architectures
Chiplet architecture has turned the package into a real performance battleground. Once multiple dies are placed side by side or stacked within the same advanced package, the quality of the die-to-die, or D2D, interface becomes one of the most important determinants of system behavior. Bandwidth is no longer a nice-to-have metric, and latency is no longer a small implementation detail. Together, they shape whether a chiplet system feels nearly monolithic or frustratingly fragmented.

Stock Selection Logic and Alpha Validation of ESG-Themed Semi ETFs
Semiconductor themed ETFs are no longer just about growth and cycles. A growing subset now layers environmental, social, and governance (ESG) criteria on top of traditional sector exposure. These ESG semi ETFs promise two things at once: access to one of the market’s most powerful secular themes, and alignment with sustainability and governance standards. The pitch is appealing, but it raises two hard questions. First, how exactly are these stocks being selected? Second, does the ESG overlay help, hurt, or leave alpha unchanged?